Planning for the future involves more than deciding how assets will be distributed after death. Many individuals also want a strategy that provides flexibility during their lifetime while helping loved ones avoid unnecessary complications later. As financial planning becomes increasingly comprehensive, trust-based planning tools continue to gain attention among families seeking greater control over their assets.
One of the most widely used estate-planning tools is a trust that allows the creator to maintain control while creating a framework for future asset management. In 2026, individuals are increasingly incorporating these arrangements into broader wealth preservation and legacy planning efforts.
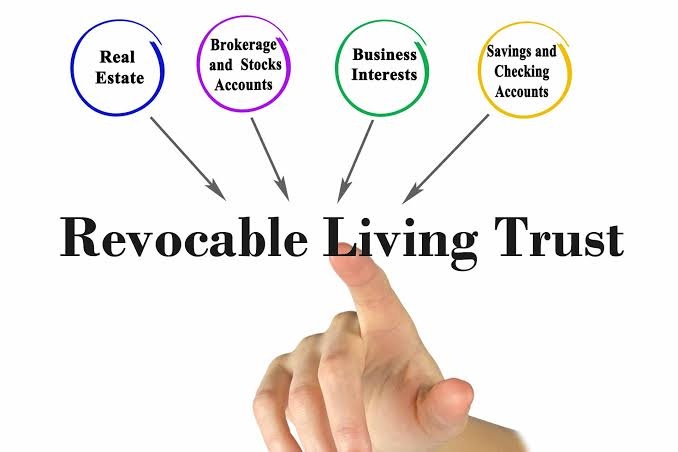
Modern families often own a combination of real estate, investment accounts, retirement assets, business interests, and digital property. Managing these assets efficiently can become challenging when no clear plan exists.
Trust-based planning can help address concerns such as:
These benefits have contributed to growing interest in flexible planning structures that can adapt to changing circumstances.
A revocable living trust is a legal arrangement created during an individual's lifetime that allows assets to be placed into a trust while maintaining the ability to modify, amend, or revoke the arrangement.
The person creating the trust, often called the grantor or settlor, typically retains significant control over the assets during their lifetime. In many cases, the grantor also serves as the initial trustee, continuing to manage trust property as they normally would.
Because the arrangement remains revocable, changes can generally be made as financial circumstances, family situations, or personal goals evolve.
After establishing the trust, assets are transferred into its ownership. These assets may include:
The trust document identifies how the assets should be managed during the grantor's lifetime and what should occur after death or incapacity.
A successor trustee is typically named to assume management responsibilities if the original trustee becomes unable to serve.
One of the primary reasons many individuals choose a revocable living trust is flexibility.
Unlike certain irrevocable arrangements, the grantor generally retains the ability to:
This flexibility allows the plan to evolve alongside changing financial and family circumstances.
For many families, maintaining control while creating a structured asset-management plan provides a balance between flexibility and long-term preparation.
Incapacity planning has become a major focus of financial and legal planning in recent years.
If a person becomes unable to manage financial affairs due to illness or injury, a successor trustee may step in according to the trust's terms. This transition can help ensure continuity in asset management without disrupting ongoing financial responsibilities.
The ability to address incapacity concerns is one reason many planners view trust-based arrangements as a valuable complement to other planning documents.
Privacy is another factor that contributes to the popularity of trust planning.
Certain estate administration processes may become part of the public record depending on applicable laws and procedures. Trust administration often allows financial matters to remain more private because asset transfers are governed by the trust document rather than through public court proceedings.
For families who value confidentiality, this can be an important consideration.
Many individuals want more than a simple transfer of assets. They may wish to establish guidelines for how wealth is managed or distributed over time.
A revocable living trust can provide instructions regarding:
These provisions can help create greater structure while reflecting the grantor's personal goals and priorities.
As digital ownership continues to expand, planning for online assets has become increasingly important.
Modern trust plans often address:
Without proper planning, these assets can be difficult for family members to identify and manage.
The inclusion of digital property is becoming a standard component of comprehensive planning efforts in 2026.
Despite their popularity, several misconceptions persist.
Trust-based planning often works alongside other important documents such as wills, powers of attorney, and healthcare directives.
Families of varying financial backgrounds may benefit from organized asset-management structures.
One of the defining features of a revocable arrangement is the ability to modify it during the grantor's lifetime.
Creating a trust document alone is not enough. Assets generally must be properly transferred into the trust for the plan to function as intended.
Understanding these distinctions can help individuals make more informed planning decisions.
Several trends continue to shape modern planning strategies.
Extended lifespans have increased the importance of incapacity planning and long-term asset management.
Blended families, multiple generations, and evolving family dynamics often require flexible planning approaches.
Digital assets are becoming a larger component of personal net worth.
Individuals increasingly seek planning tools that provide clarity, efficiency, and continuity.
These trends are encouraging more families to review their planning structures regularly.
Every family has unique financial circumstances and objectives. Factors such as asset composition, family structure, business ownership, charitable goals, and long-term wealth preservation strategies may influence planning decisions.
A comprehensive review of these factors can help determine whether trust-based planning aligns with an individual's goals.
Regular updates are equally important. Significant life events such as marriage, divorce, births, deaths, business changes, or major asset acquisitions may justify revisiting existing plans.
Creating a thoughtful legacy plan involves balancing flexibility, control, and long-term asset protection. Trust-based arrangements can provide an organized framework for managing assets during life while supporting a smoother transition for future generations.
As financial planning continues to evolve, individuals are placing greater emphasis on proactive preparation, continuity, and adaptability. With proper implementation and periodic review, a well-structured plan can help families preserve assets, reduce uncertainty, and maintain greater confidence about the future.
This post has been authored and published by one of our premium contributors, who are experts in their fields. They bring high-quality, well-researched content that adds significant value to our platform.
Photography Shots is your source for photography tips, camera guides, editing tutorials, and creative inspiration. Capture moments, tell stories, and improve your photography skills.